Probate & awaiting sale
Arrange cover around the property’s circumstances. Tell us who has responsibility for the estate or building and how long it has been empty.
An empty home.
One less thing to worry about.
For homes awaiting sale, going through probate or between tenants. We help you find cover that reflects why the property is empty and how it will be looked after.
Personal advice · Mon–Fri, 9am – 5.30pm
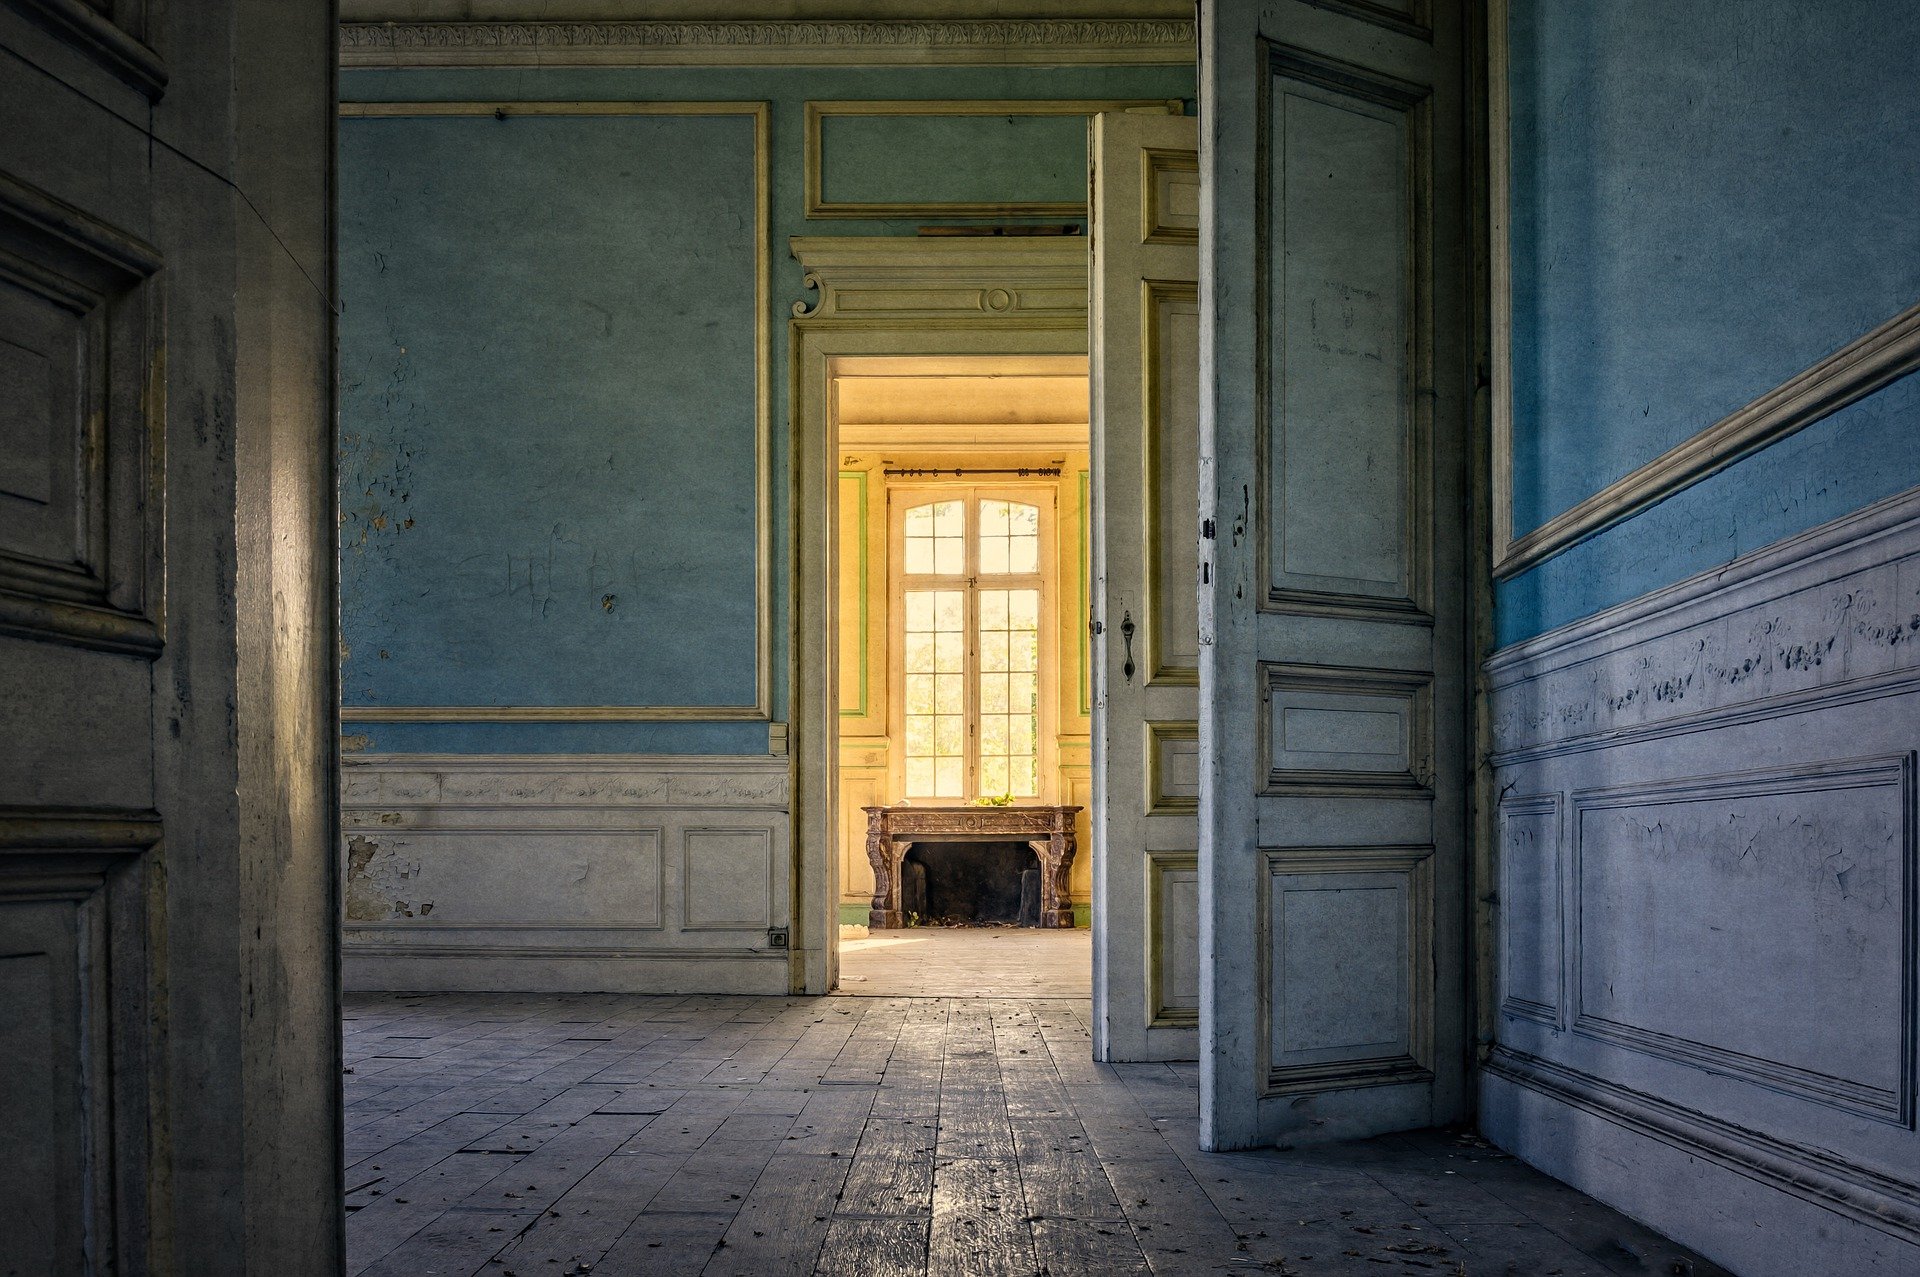
Unoccupied home insurance is designed for a property that is empty for longer than its usual home insurance allows. The Home Insurer arranges specialist cover for vacant homes, including probate and gaps between tenancies, with the level of protection and conditions explained before you buy.
Arrange cover around the property’s circumstances. Tell us who has responsibility for the estate or building and how long it has been empty.
Discuss cover during a letting gap and how the policy should change when new tenants move in.
We can discuss both the building and any contents remaining inside. Check the quotation for the events insured and the contents limit.
Cover is subject to underwriting, policy terms, limits, conditions and exclusions. Your quotation and policy documents confirm what is included.
Policies for empty homes vary considerably. Some restrict protection to fire, lightning, earthquake and aircraft risks; others offer a wider range of insured events. We focus on understanding the protection you need and explaining what is actually covered. An annual policy with an agreed cancellation arrangement may be worth comparing with a short-term policy.
Inspection frequency, security, heating and draining-down requirements are policy-specific. Ask what records you must keep. If you plan renovation work, disclose it before it starts: an empty-home policy may not permit the work.
Your premium depends on the rebuild value, location, condition, length of vacancy, security and claims history. Compare the total cost for the time you expect to need cover, including cancellation fees and any refund conditions.
Send us your renewal terms if you have them. We can compare the cover, excesses and conditions with the options available through our panel and explain our recommendation.
Director · The Home Insurer
Our empty-property team can explain inspection requirements, heating or draining-down conditions, and what happens when the house is sold or occupied again. Tell us if regular visits would be difficult.
Talk to our team on 01832 735388Something specific to your property?
Talk it through with us.
Your existing policy sets the unoccupancy limit and what happens once it is exceeded. Check the wording and tell the insurer before the property is left empty for longer. We can discuss specialist cover if the existing policy no longer meets your needs.
We can consider probate properties. Tell us who is arranging the insurance, the ownership or estate position, whether contents remain and how the property will be checked. The correct insured name needs to be agreed.
Some policies offer a pro-rata refund when cancelled, subject to their conditions and any fees. Ask us to confirm the applicable cancellation terms in writing before buying. Do not assume every annual or short-term policy works the same way.
The required inspection interval depends on the insurer. Tell us how often visits are realistic so we can look for suitable terms. Your policy will set out the inspection and recording requirements.
We can discuss longer-term vacancies and boarded properties with specialist insurers. Give us an accurate description of the condition and any planned works. Cover is not guaranteed, particularly for severely deteriorated buildings or planned demolition.
Tell us about your property and we’ll help you understand the options available.