Your building & roof
Discuss the rebuild value, thatching materials, wall construction and any listed status so the quotation reflects the home you actually own.
A home with character.
Cover that understands it.
Specialist insurance for thatched cottages, listed thatch and homes with unusual construction. Talk to a team that takes the time to understand your roof, your heating and the way you live.
Personal advice · Mon–Fri, 9am – 5.30pm
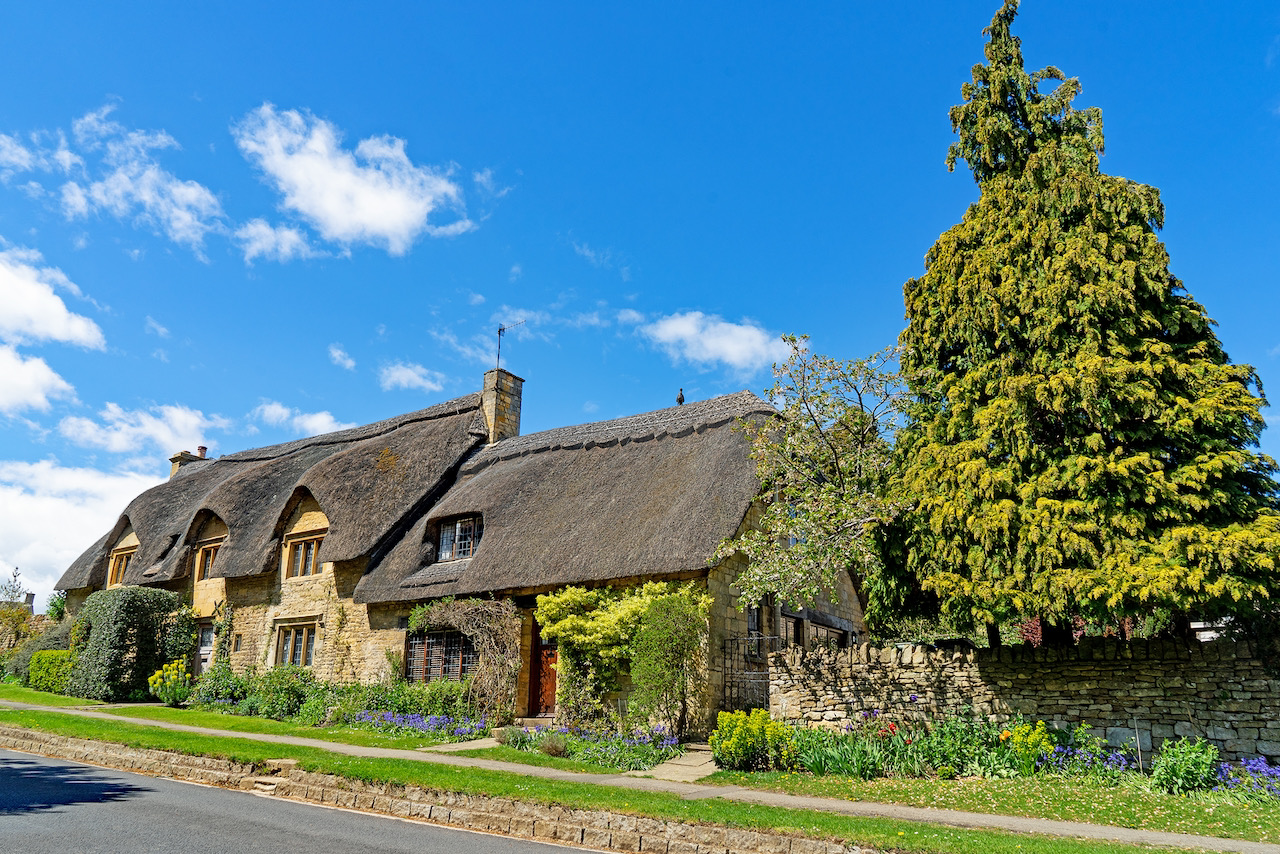
Thatched home insurance covers a thatched building and, when selected, its contents against insured events. The Home Insurer is a UK specialist broker that compares policies from a limited panel, with particular attention to fire precautions, roof condition and the cost of specialist repairs.
Discuss the rebuild value, thatching materials, wall construction and any listed status so the quotation reflects the home you actually own.
Ask about contents, valuables and possessions away from home. These are separate choices, with their own limits and conditions.
Tell us about holiday use, letting, an empty period, renovation work, flooding or previous subsidence. Each needs to be disclosed and agreed.
Cover is subject to underwriting, policy terms, limits, conditions and exclusions. Your quotation and policy documents confirm what is included.
A solid-fuel stove or open fire needs careful assessment. Insurers can set conditions for chimney height, sweeping, lining and maintenance. Tell us exactly what is installed and how it is used; do not assume another owner’s requirements apply to your property. We will explain the requirements in your quotation, including any reports needed before or after cover starts.
Routine maintenance, wear and tear and replacing an ageing roof are different from damage caused by an insured event. Check the schedule for fire conditions, excesses, exclusions and any deadline for supplying inspection reports.
The price depends on your rebuild value, roof and wall materials, heating, location, occupancy and claims history. Comparing the premium alongside fire conditions, excesses and contents limits gives a more useful result than comparing price alone.
Send us your renewal terms if you have them. We can compare the cover, excesses and conditions with the options available through our panel and explain our recommendation.
Head of Sales · The Home Insurer
Our thatch team will talk through the details of your home and explain the conditions attached to the recommended policy. Have your roof and electrical inspection reports to hand if you have them.
Talk to our team on 01832 735388Something specific to your property?
Talk it through with us.
We can approach specialist insurers for listed thatched homes and unusual materials such as cob. Tell us the listing details and construction, as well as any planned repairs. Acceptance and terms depend on the property.
Yes, you can ask us to assess it. We will need the stove and chimney details, inspection and sweeping information, and relevant fire precautions. Cover for its use must be agreed by the insurer.
Have your most recent thatch and electrical inspection reports ready. The accepted age of reports and any remedial work depend on the insurer’s requirements. If a report is missing or out of date, tell us so we can discuss the options.
Check the individual quotation. Tell us about flood history or known risk; we can investigate flood cover and, where the full eligibility criteria are met, Flood Re options. A pre-2009 build date alone does not establish eligibility.
Tell us about your property and we’ll help you understand the options available.