Historic subsidence
Tell us when the issue happened, what caused it and whether there has been further movement. Older problems still need accurate disclosure.
A repaired home.
A future worth protecting.
Specialist home insurance for properties with a history of subsidence, landslip or heave. We look at what happened, how it was repaired and the evidence of stability.
Personal advice · Mon–Fri, 9am – 5.30pm
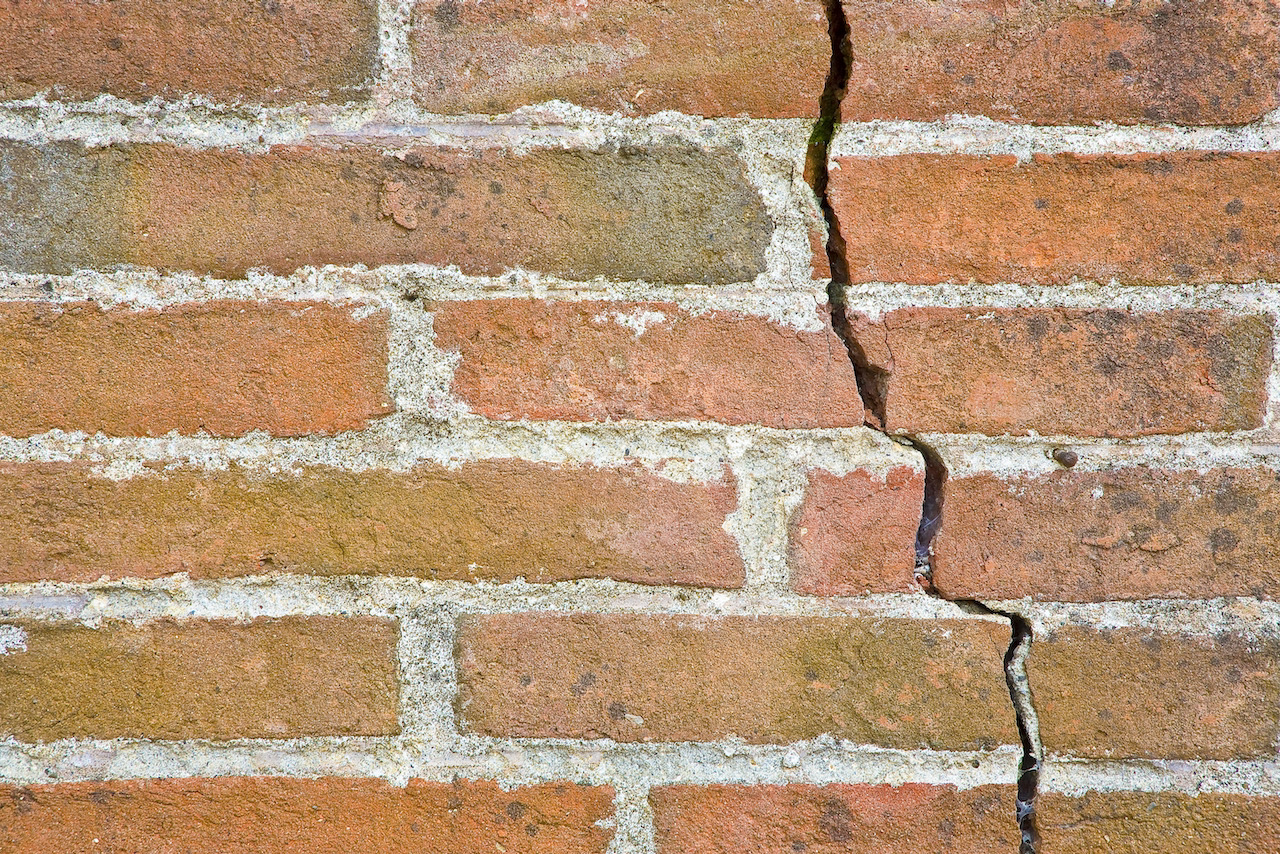
Subsidence insurance is cover for subsidence within a property insurance policy, subject to its terms. The Home Insurer helps owners of previously affected homes seek cover for future insured damage, using the history of the problem, professional repairs and supporting reports to discuss the risk with specialist insurers.
Tell us when the issue happened, what caused it and whether there has been further movement. Older problems still need accurate disclosure.
Underpinning, other repairs and evidence of stability may help insurers assess the property. Share the relevant professional records.
Check whether subsidence, landslip and heave are included, and what excess applies. Acceptance of the home alone does not confirm those risks are covered.
Cover is subject to underwriting, policy terms, limits, conditions and exclusions. Your quotation and policy documents confirm what is included.
If movement is suspected or a claim is still open, contact the existing insurer and explain the position before changing cover. A new policy is not a way to transfer damage that has already happened. For a repaired property, the cause, quality of remedial work and subsequent stability are key details for an underwriter.
Cracks can have different causes and need appropriate professional assessment. Insurance is not a survey or a guarantee that a building is stable. Check for subsidence exclusions, special conditions and a separate subsidence excess.
The cause and age of the issue, repair evidence, stability, location and rebuild value all influence the premium and excess. Compare a policy including subsidence with care: a cheaper quote may exclude the very risk you need covered.
Send us your renewal terms if you have them. We can compare the cover, excesses and conditions with the options available through our panel and explain our recommendation.
Head of Renewals · The Home Insurer
Our team will talk through the property’s history and ask for repair reports, warranties or monitoring evidence where available. These details help us explain the risk to underwriters and compare the terms offered.
Talk to our team on 01832 735388Something specific to your property?
Talk it through with us.
We can approach insurers for professionally repaired and underpinned homes. Provide the repair history, reports and warranties, plus details of any later movement. Cover is subject to the insurer’s assessment.
No. Time since the problem can help an insurer assess the risk, but it does not guarantee standard terms. The cause, repairs, continuing stability and policy wording still matter.
Discuss the open claim and any proposed change with your current insurer and adviser first. A new policy will not retrospectively cover the existing damage, and future subsidence cover may be restricted.
It may be different and can be substantially higher. Ask for the subsidence excess to be identified separately in the quotation, along with any other special terms.
Tell us about your property and we’ll help you understand the options available.