Previously flooded homes
Tell us when flooding happened, how severe it was and what repairs followed. Previous flooding does not automatically end the search for cover.
A flood history.
A fresh look at your cover.
For homes that have flooded before or sit in a flood-risk area. We explore specialist options, including Flood Re where the property meets its eligibility criteria.
Personal advice · Mon–Fri, 9am – 5.30pm
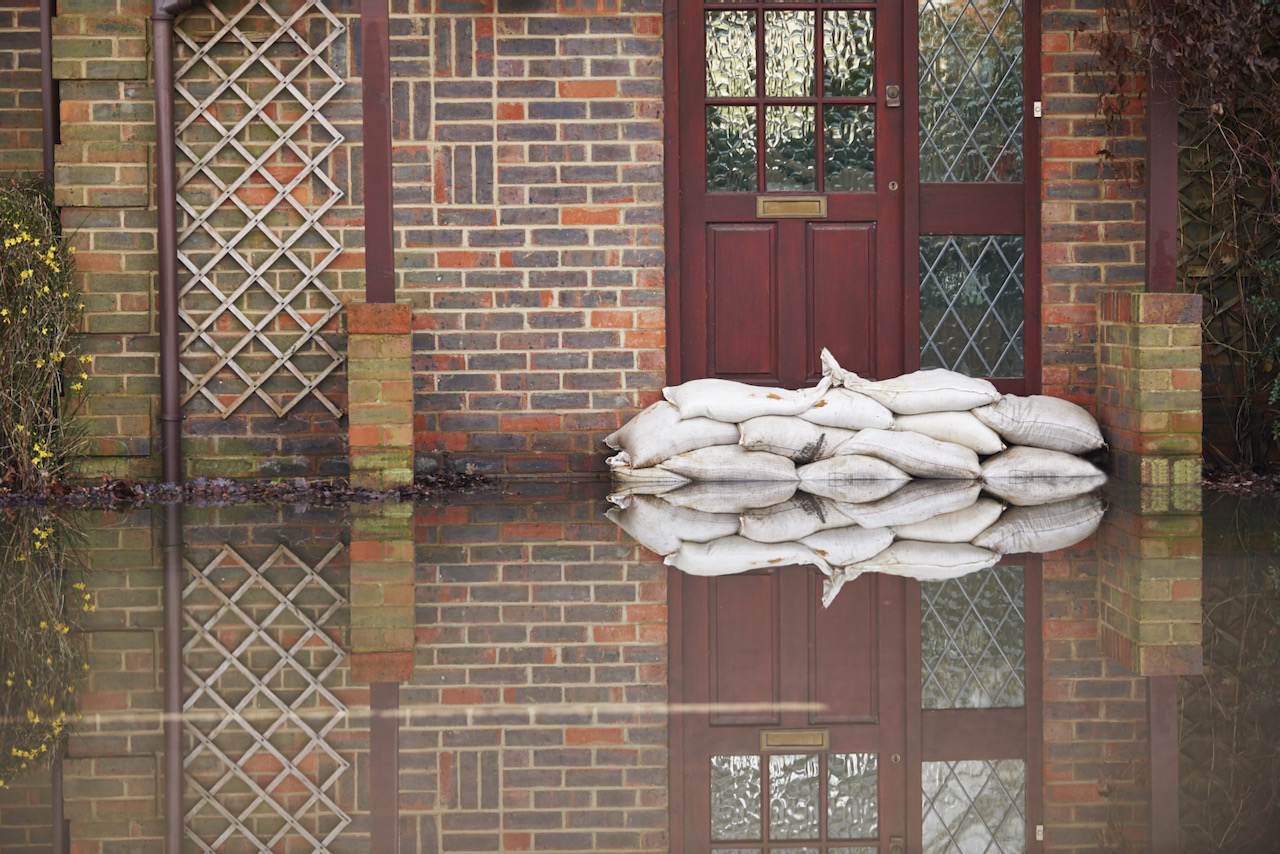
Home flood insurance covers flood damage where it is included in the policy, subject to limits, excesses and conditions. The Home Insurer helps owners of flood-risk homes compare suitable options from a limited panel and considers Flood Re-supported cover where the full eligibility criteria are met.
Tell us when flooding happened, how severe it was and what repairs followed. Previous flooding does not automatically end the search for cover.
We can explore cover supported by Flood Re for eligible homes. Eligibility and an insurer’s offer need to be assessed separately.
Let properties, commercial buildings and homes outside Flood Re’s criteria may need different specialist options. Tell us how the building is used.
Cover is subject to underwriting, policy terms, limits, conditions and exclusions. Your quotation and policy documents confirm what is included.
Flood Re is a reinsurance scheme that operates behind participating home insurers. It is not a policy you buy directly. Build date, Council Tax arrangements, occupancy and property type all matter. The insurer decides whether to use the scheme and sets your premium. Use Flood Re’s eligibility guidance alongside a discussion of your own circumstances.
Read the full Flood Re eligibility criteria.
Check that flood is actually included, the flood excess, any maximum payout and the conditions for using protection measures. A policy that excludes flood does not solve a need for flood protection.
Flood history, location, rebuilding cost, contents and the terms available through the insurer affect the price. Compare the flood excess and payout limit as well as the premium. Installing protection measures does not guarantee a discount; disclose them so they can be considered.
Send us your renewal terms if you have them. We can compare the cover, excesses and conditions with the options available through our panel and explain our recommendation.
Head of Renewals · The Home Insurer
Our flood team will ask about previous events, repairs and protection measures. We can explain the flood excess and any limit on flood claims, helping you understand the practical difference between quotations.
Talk to our team on 01832 735388Something specific to your property?
Talk it through with us.
Yes, we can investigate specialist options. Provide details of the flooding, claim and repairs. Availability and terms depend on the property and the insurer’s assessment.
No. Build date is one condition within wider criteria that also consider the property, Council Tax arrangements and occupancy. The insurer must assess the risk and decide whether to use Flood Re.
Properties rented to people outside the owner’s immediate family generally do not qualify. We can discuss specialist alternatives for let property. Check the full criteria for the particular ownership and occupancy arrangement.
They may influence an insurer’s assessment, but savings are not guaranteed. Tell us what is installed and maintained. If a policy requires protection measures to be deployed, those conditions need to be understood and followed.
We can discuss specialist commercial options, including FloodFlash where suitable. Trigger-based cover works differently from a conventional damage claim: the agreed flood trigger and payout need careful consideration.
Tell us about your property and we’ll help you understand the options available.